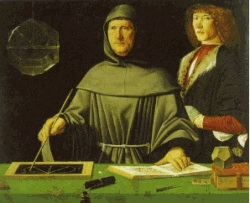
Not Luca Pacioli?
Assets = Liabilities + Owners’ Equity.
Ouch! He was right: The first recorded history of the description of double entry bookkeeping was done by Benedikt in 1458 in his work: Book on the Art of Trade.
Although only in a short appendix, it was the first description of what was as one of the world’s great intellectual breakthroughs — modern accounting. This craft enables merchants, entrepreneurs and their investors to keep track of every penny they received or spent.
Thanks to accounting, it allowed people to organize massive amounts of information into journals and then produces summary financial statements — primarily income statements and balance sheets. The income statement showed, over a time period, total revenues minus total expenses, leaving either a profit or loss. The balance sheet was compiled at a point in time and illustrated the assets, the debts, and the difference in the owners’ equity. These financial tools enabled the entrepreneurs to allocate resources more effectively. As an example, if the business person owned two restaurants, they could look at each income statement and seeing the profits or loss, they could determine which one to close and which one to invest more money in.
On a larger scale, trading ships were soon analyzed by income statements and more and more decisions began to be understood using the tools of accounting, leading to greater efficiency of capital, the savings of a society. Out of the income statement came the intellectual miracle of the return on investment (ROI) which allowed investors to compare investments mathematically with the simple ROI formula and soon after, the business community started to add risk to the analysis which was another game changer. An entrepreneur might ask: if we could make a $1,000 on investment A and a $1,000 on investment B, which one has the least risk thereby making the investment safer and better? This combination of risk and return into business analysis became the basis of modern business theory and decision making.
The balance sheet had a great effect as well. This intellectual tool shows how all assets are financed by simplifying accounting into a simple equation:
Assets = Liabilities + Owners’ Equity.
The extended accounting equation must balance:
|
‘A + E = L + OE + R’
|
(where A = Assets, E = Expenses, L = Liabilities, OE = Owner’s Equity and R = Revenues)
- So therefore, ‘Debit Accounts (A + E) = Credit Accounts (L + R + OE)’.
- Debits are on the left and increase a debit account and reduce a credit account. Credits are on the right and increase a credit account and decrease a debit account.
Essentially, the equation shows that everything owned can be financed with either debt or equity, or a combination of both. With this simple intellectual insight, as powerful as E=hv (Planck’s equation) owners, workers and entrepreneurs were able to begin to value their assets more accurately and to sell them to others for what they were worth. People began to make better and wiser decisions and became more financially literate. As markets grew around the world, wealth began to be created on a scale never seen before, lifting millions and millions of people out of poverty.
via So, Who Invented Double Entry Bookkeeping? Luca Pacioli or Benedikt Kotruljević? | Steve Mariotti.